
Credit Score Tracker Spreadsheet
All three bureau scores, your utilization and a goal line, in one honest file.
View on Etsy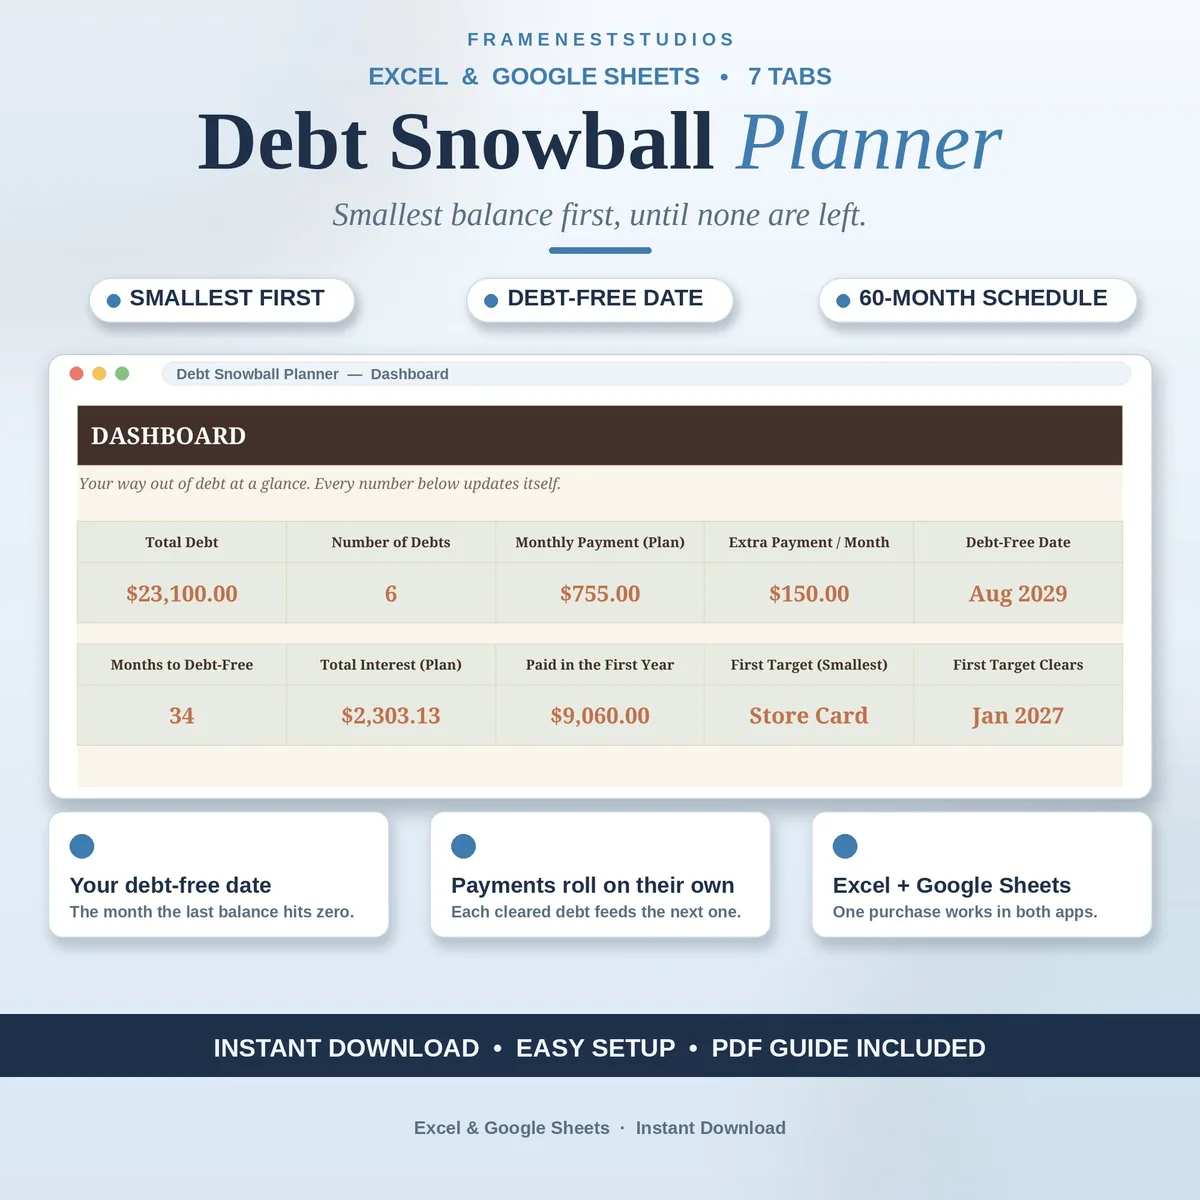
Five balances, five minimum payments, five different days, and somehow nothing ever shrinks. This debt snowball planner lines your debts up smallest first, rolls each freed payment into the next one, and gives you a debt-free date to circle.
Sale price in our Etsy shop right now. Checkout, payment and instant delivery are handled by Etsy.
Debt feels heaviest when it is spread everywhere at once. A store card here, a loan there, minimums leaving on different days and balances that barely move. The snowball method fixes the order of attack: smallest balance first, minimum payments on everything else, and every spare dollar aimed at the one target until it is gone. This planner builds that sequence for you and keeps it updated as you pay.
The Snowball Schedule works out sixty months of payments. Every debt gets its minimum, everything left over goes at the smallest balance, and when a debt clears, its whole payment rolls into the next debt inside the schedule by itself. That roll-on is the step people usually give up on when they track it by hand. The Monthly Payment Log then sits beside the plan, showing what the schedule said next to what you really paid.
The Debt List holds up to 8 debts, each with creditor, balance, APR and minimum payment, numbered in payoff order automatically. The Payoff Chart shows your total balance falling month after month, with the total interest the plan will cost laid out honestly. And the Budget Link tab turns the whole plan into one monthly amount for your budget, with per-paycheck figures for weekly or two-weekly pay.
The things buyers ask us most.
A normal tracker lists what you owe. This planner is built around the snowball method itself: debts are attacked smallest balance first for early wins, and when one clears, its whole payment rolls into the next debt automatically inside the sixty month schedule. That roll-on is the part people usually give up on, and here the sheet does it for you.
The Debt List holds up to 8 debts. Fewer is completely fine: leave the spare rows empty and the plan ignores them. If you have more than 8, group small balances that share a creditor onto one line, or clear the tiniest debts first and add the next one as a row frees up.
Yes, at any time. Raise it after a pay rise or lower it for a tight month, and the payoff months, the interest total and your debt-free date all rebuild themselves from the new number. The plan is a living schedule, not a contract, so it adjusts to real life instead of breaking the first time a month goes sideways.
Either one. The access PDF gives you a Google Sheets copy in one click, and the BLANK workbook opens in Excel 2021 or Microsoft 365. Both versions carry the same 7 tabs and the same working formulas, and the EXAMPLE file shows realistic sample debts already turned into a dated plan before you type a word.
Three more workbooks from the same shelf.
All three bureau scores, your utilization and a goal line, in one honest file.
View on EtsyOne loan, in depth: your payoff date, extra payment savings and a refinance check.
View on EtsyUp to 4 car loans, a snowball or avalanche plan, and your debt-free date.
View on Etsy